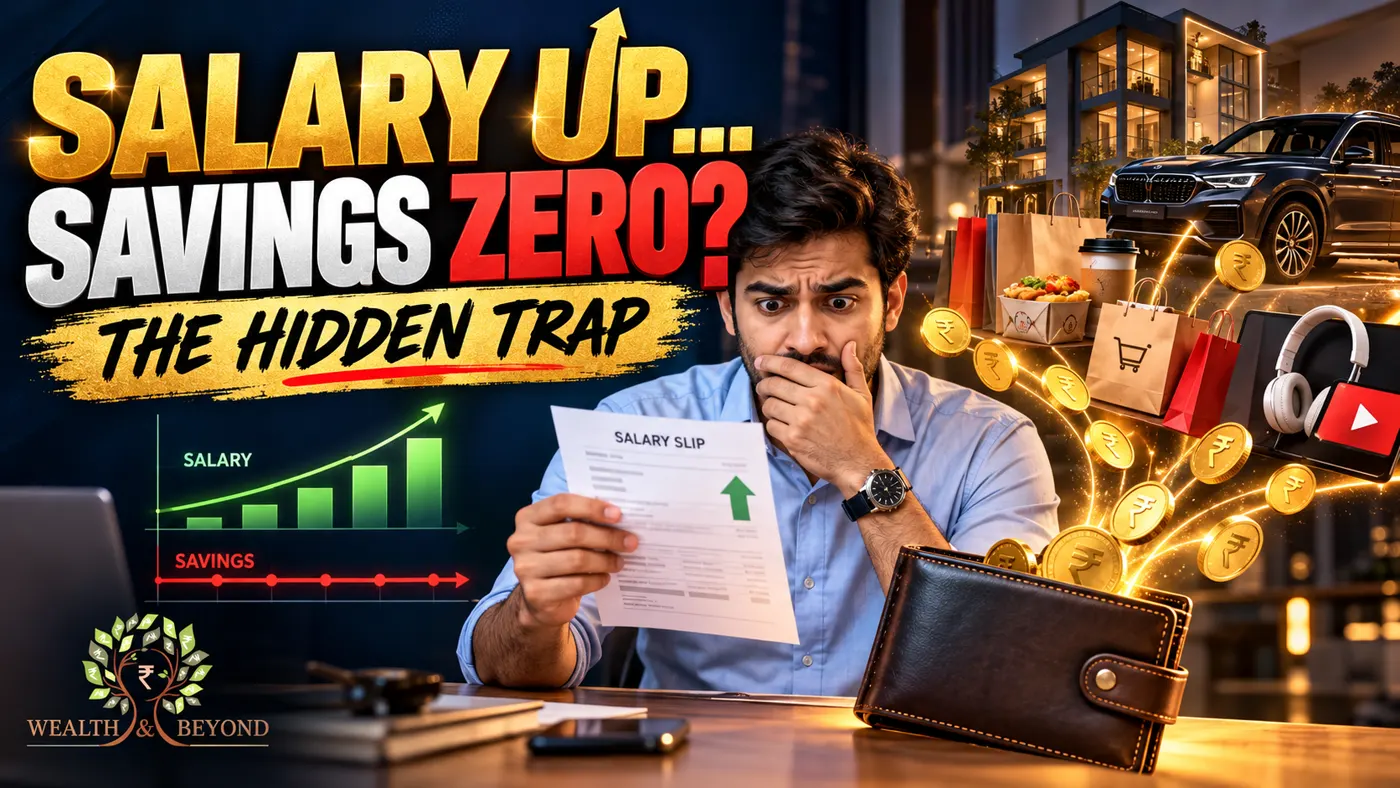
A client came to our Nagpur office last month, visibly pleased with himself. His salary had gone up forty percent over three years, two promotions and a job switch. He was expecting us to tell him his finances looked great. Instead, we pulled up his bank statements and showed him something he hadn't noticed: his savings, in absolute rupees, had barely moved. The car had changed, the flat had changed, the weekend plans had changed. The number left over at the end of the month had not.
This is not a story about a careless person. He is diligent, numerate and genuinely surprised. It is a story about how income and expenses quietly move together unless you force them apart, and it happens to almost everyone who has never deliberately interrupted it.
What Lifestyle Inflation Actually Is
Lifestyle inflation, sometimes called lifestyle creep, is the gradual rise in spending that tracks a rise in income. It is not one big splurge. It is a hundred small ones: a slightly better phone upgrade cycle, a subscription added here, a cheaper flight swapped for a better seat there. None of these decisions feels reckless in the moment. Stacked over several raises, they consume the entire increment, every time.
The reason this matters more than it sounds is that your capacity to build wealth is not driven by how much you earn. It is driven by the gap between what you earn and what you spend. A person earning fifteen lakh a year and saving four is in a stronger position than a person earning thirty lakh and saving two, even though the second number looks more impressive on a resume. It is the same gap that ultimately decides how close someone is to genuine financial independence.
Why It's Invisible Until You Measure It
Nobody sits down and plans to spend their entire raise. It happens because the extra money arrives in the same account as everything else, with no separate label attached to it. Humans are remarkably good at rationalising each individual upgrade as sensible and reasonable, while being almost blind to the cumulative pattern across several years. We have written before about how money psychology shapes decisions that feel rational one at a time but add up to something nobody would have chosen deliberately.
There is also a social layer to it. Income growth tends to move people into new peer groups, whether that is a different floor at the office, a new friend circle, or relatives who expect a certain standard at family functions. Matching that standard feels less like indulgence and more like obligation, which makes it even harder to notice as a choice.
What Lifestyle Inflation Looks Like
A two-wheeler becomes a hatchback, then a sedan. A shared flat becomes a bigger one, then a bigger one again, often faster than the household actually needs.
What It Costs You
Not the individual purchases, which are usually fine on their own, but the compounding years of a savings rate that never actually improves as your career does.
The Psychology of "I Deserve This"
There is nothing wrong with enjoying the fruits of hard work, and we are not arguing for a life of deprivation. The trap is not the upgrade itself, it is upgrading with the entire increment, every single time, so that the phrase "I deserve this" gets applied to a hundred percent of every raise rather than a portion of it. Over a working life, that difference decides whether you retire comfortably or anxiously.
A Simple Rule of Thumb for Any Raise
The framework we suggest to most clients is deliberately simple, because complicated rules rarely survive contact with real life. Split every increment roughly in half. One half goes towards increasing your SIP, your recurring deposit, or whatever structured saving you already run. The other half is yours to spend however you like, guilt-free, because you have already protected your future self.
Why a fixed split works better than willpower
Willpower is a finite resource and a poor long-term strategy. A fixed rule removes the need to negotiate with yourself every time your salary slip changes. You decide once, calmly, before the excitement of a new number clouds the decision, and then the rule runs itself.
Adjusting the split as your base is covered
Early in a career, when your base expenses are still a meaningful share of income, a fifty-fifty split is sensible. Once your core financial plan shows your essential goals are well funded, you can shift the ratio further towards savings, perhaps seventy percent of future increments going to investments, since your lifestyle has already caught up to a comfortable level. This is the same logic we apply when we build a full advisory relationship around a client's income trajectory rather than a single snapshot.
Automate Before You See the Number
The single most effective tactic we have seen work in practice is timing. The moment your revised salary is confirmed, before the first higher credit lands in your account, increase your SIP or recurring investment by the amount you have decided to save. If you wait even one month, the higher number starts to feel normal, and normal is hard to give up.
Most banks and mutual fund platforms let you set this up in a few minutes. Treat it the same way you treat a loan EMI, which is to say, non-negotiable and invisible to your day-to-day spending decisions because it never reaches your spendable balance in the first place.
A Tale of Two Colleagues
Picture two people who joined the same company at the same salary and received identical raises over ten years. One increased her SIP every time her salary rose, keeping her lifestyle spend growing more slowly than her income. The other upgraded his lifestyle in step with every hike, keeping his savings rate flat throughout.
By year ten, their take-home pay is nearly the same. Their invested corpus is not even close. The difference is not talent, luck or even income. It is the decision, repeated at every single raise, about where the extra rupee went. Run your own numbers through a compounding calculator and the size of that gap over a full career becomes hard to ignore.
How This Compounds Across a Career
The earlier in a career you interrupt lifestyle inflation, the larger the eventual payoff, simply because there are more years for the redirected money to compound. A habit formed at thirty has decades to work. The same habit formed at fifty has far less runway, even if the absolute rupee amounts saved each year look similar.
This is also why we encourage clients to treat each promotion as a planning checkpoint rather than just a celebration. A short conversation with an advisor at every raise keeps the habit from drifting, the same way a dentist checkup catches small problems before they become expensive ones. It is a smaller, calmer version of the goal-setting exercise we described when writing about building a retirement corpus, just applied every year instead of once.
Watch the Categories That Creep Fastest
Not all spending inflates at the same pace. Rent and vehicle upgrades tend to be the biggest and most permanent jumps, because once you move to a bigger flat or a bigger car, reversing that decision feels like a step backwards in a way that cutting a subscription never does. Food delivery and subscription services creep more quietly, a few hundred rupees at a time, but across a dozen apps the total is often larger than people expect when they actually tally it.
| Spending Category | How Fast It Creeps | How Reversible It Is |
|---|---|---|
| Rent or home size | Slow, but large jumps | Difficult, feels like a downgrade |
| Vehicle | Moderate, every few years | Difficult once financed |
| Dining and food delivery | Fast and continuous | Easy to scale back |
| Subscriptions and apps | Fast, often unnoticed | Very easy to cancel |
| Travel and leisure | Seasonal, tied to bonuses | Easy to plan around |
| Gadgets and upgrades | Moderate, cycle-driven | Easy to delay a cycle |
Don't Forget the Savings You Don't See
Lifestyle inflation discussions usually focus on the money that lands in your bank account, but a meaningful part of your long-term security is already being built quietly through retirement contributions. Your EPF balance grows with every salary revision automatically, since the contribution is a percentage of basic pay, not a fixed rupee figure. That is one part of the equation that inflates with your income without any decision from you, which is exactly why the discretionary part deserves the same deliberate treatment.
The mistake we see most often is treating the EPF growth as "enough" and assuming retirement is handled, when in reality it usually covers only a portion of what a comfortable retirement will cost by the time you get there. Lifestyle inflation in your thirties and forties, left unchecked, often means this gap between automatic savings and your actual retirement need widens rather than narrows.
What to Do With Bonuses and Windfalls
Annual bonuses deserve a different rule than monthly increments, because they arrive as a lump sum rather than a recurring change to your baseline. The temptation to spend the entire bonus on something large is strong precisely because it feels separate from your regular budget. Apply the same split logic, but be even more deliberate: decide the savings portion before the bonus hits your account, and route it directly into investments or towards paying down any high-cost debt first.
When Lifestyle Inflation Is Actually Fine
We want to be fair to the other side of this. If you have been underspending relative to your means for years, genuinely under-insured, under-housed or skipping experiences that matter to you, a deliberate lifestyle upgrade funded by a raise is not a mistake. The problem is only when the upgrade happens by default, consumes the whole increment every time, and nobody ever checks whether the savings rate is actually improving as income rises.
Common Mistakes We See
A recurring one is confusing a higher gross salary with higher disposable income, without accounting for the fact that tax takes a growing bite as you move up slabs. Another is financing a lifestyle upgrade through credit rather than current income, which locks in the higher spend as a fixed obligation long after the novelty fades. We also see people increase spending the moment a raise is announced, before it has even landed, based on the expectation of more money rather than the money itself.
Families managing finances across two locations, including our NRI clients, face an extra version of this problem when a stronger foreign salary quietly resets what feels normal to spend once they are back in India.
A Short Checklist Before Your Next Raise
Decide your split in advance, automate the savings portion on day one of the new salary, confirm your emergency fund is still sized for your new expenses, give yourself permission to enjoy the rest without guilt, and revisit the plan with a professional once a year rather than letting it drift silently. None of this requires extraordinary discipline. It requires one decision, made calmly, before the excitement of a bigger number takes over.
How Wealth & Beyond Can Help
| What You Need | How We Help | Link |
|---|---|---|
| A savings rate that actually improves with every raise | We set a target split for increments and bonuses and track it against your real goals | Financial Planning |
| Help automating SIPs each time your salary changes | We review and adjust your investment structure every time your income moves | Wealth Mgmt |
| Understanding what a raise actually adds after tax | We map your slab and effective tax rate so you know your true disposable increase | Tax Planning |
| A check on whether your current spending is already overextended | We review your portfolio and cash flow together and flag where creep has crept in | Portfolio Review |
Frequently Asked Questions
What is lifestyle inflation?
Lifestyle inflation, also called lifestyle creep, is the tendency to spend more as you earn more, so that every raise quietly gets absorbed into a slightly better car, a bigger flat or more frequent outings, leaving your savings rate roughly where it always was.
Why don't I save more when I earn more?
Most people don't decide to overspend a raise, it happens by default because the extra money lands in the same account as everything else and gets spent on whatever feels like the next reasonable upgrade, with no automatic rule diverting part of it to savings first.
How much of a salary hike should I save?
A reasonable starting rule is to split any increment roughly 50-50, directing half towards savings and investments and allowing the other half to improve your lifestyle, though the exact split can shift in your favour over time as your base needs are already met.
What are common lifestyle creep examples in India?
Typical examples include upgrading from a two-wheeler to a car and then to a bigger car with each hike, moving to a larger rented flat than you need, switching from occasional dining out to frequent food delivery, and subscribing to several overlapping streaming and app services that quietly add up.
How do I avoid lifestyle inflation after a promotion?
The most reliable method is to automate the increase in your SIP or recurring deposit on the same day your new salary starts, before the higher number in your account has a chance to normalise, so the saving happens by default rather than by willpower.
Does lifestyle inflation affect financial independence?
Yes, significantly. Financial independence depends on the gap between your income and your expenses, not on your income alone, so if expenses rise in lockstep with every raise that gap never widens and the timeline to independence keeps slipping further away.
Is it wrong to upgrade my lifestyle after a raise?
No, enjoying some of your success is reasonable and sustainable. The issue is not upgrading itself but upgrading with all of the increment every single time, with no portion set aside first, so that your savings rate never actually improves as your career progresses.
How can a financial advisor help with lifestyle inflation?
An advisor can set a clear savings rate target tied to your goals, build the automation that enforces it, and review it each time your income changes, so the decision is made once calmly rather than being renegotiated with yourself every time a raise arrives.
Just Got a Raise? Decide Where It Goes Before You Spend It
Talk to us before the new salary normalises. We will help you set a split that protects your future without making today feel like a sacrifice.
Plan Your Next Raise